


You can get sued for almost anything. That doesn't mean the lawsuit will succeed. It doesn't even mean the other side has a good case. But it does mean your hard-earned assets could become a target. That's why successful business owners don't wait until they're facing a lawsuit to think about asset protection. They plan ahead.
One of the most effective tools for doing that is a Domestic Asset Protection Trust (DAPT). A properly structured DAPT can protect certain assets from future creditors while still allowing you to benefit from those assets. The key is that it has to be established before legal trouble begins.
If you've spent years building a successful business, investing in real estate, or growing your personal wealth, understanding when a DAPT makes sense could save you from making one of the biggest asset protection mistakes I see: waiting until it's too late.
What Is a Domestic Asset Protection Trust?
A Domestic Asset Protection Trust (DAPT) is a special type of irrevocable trust that allows you to transfer assets out of your personal ownership while remaining a beneficiary. That means you can still benefit from the assets, even though they're legally owned by the trust.
Think of a DAPT as another layer of protection. I say "another layer" because that's exactly what it is. A DAPT doesn't replace your LLCs. It doesn't replace your revocable living trust. It doesn't replace insurance. It works alongside those strategies to help protect certain personal assets from future creditors.
Unlike many irrevocable trusts, a properly structured DAPT still allows you to benefit from the assets inside the trust. Depending on how it's drafted and the laws of the state where it's created, you may still receive distributions, sell assets inside the trust, and continue managing your wealth while creating an additional legal barrier between those assets and future lawsuits.
You won't serve as the independent trustee responsible for making distributions, but you may be able to serve in a separate investment role. For example, if you transfer a brokerage account into a DAPT, you may still be able to direct how that money is invested without having unrestricted access to withdraw the assets whenever you want.
That's why I don't look at a DAPT as a standalone strategy. It's one piece of a comprehensive asset protection plan.
Can You Set Up a DAPT After You're Sued?
No. And this is where people get themselves into trouble.
A lot of people think, "If I ever get sued, I'll just transfer my house to my spouse," or "I'll move that investment account into a trust," or "I'll deed my rental property to my kids." That's not asset protection, that's called a fraudulent transfer.
If the lawsuit, accident, or other liability happened before you moved the asset, a judge can unwind that transaction and treat it as though it never happened. You don't get to wait until the fire starts before buying the fire insurance. That's why every asset protection strategy we recommend is built around future, unknown risks, not problems that already exist. If you're planning after the lawsuit, you're planning too late.
And don't assume you're safe just because nobody has filed a lawsuit yet. If you were involved in an accident last month, for example, a potential creditor claim may already exist. Transferring assets into a DAPT afterward doesn't magically make that liability disappear.
Even when you establish a DAPT before any problems come up, state laws may give certain creditors a period of time to challenge transfers into the trust. The waiting periods and exceptions vary by state, so don't assume every asset becomes completely untouchable the moment you transfer it.
A Real Example of Asset Protection Done Right
Here’s what this looks like in the real world. One of our clients had done everything right. They owned multiple businesses, investment accounts, and real estate. Their LLCs were in place. Their S corporations were structured properly. They had an estate plan. But because they'd built significant wealth and had meaningful liability exposure, we recommended adding another layer of protection with a Nevada Domestic Asset Protection Trust. Years later, that client lost a lawsuit.
The creditor obtained a judgment for roughly half a million dollars and immediately served the client's bank with a writ of garnishment. The bank's first reaction was exactly what you'd expect: "We've got a court order. We have to pay this." But there was one problem. The money didn't belong to the client personally, it belonged to the Domestic Asset Protection Trust.
Once we stepped in and explained how the account was titled, how the trust was structured, and why those assets were protected under Nevada law, the bank backed down. The garnishment never reached the protected funds because they weren't the client's assets anymore. They belonged to the trust.
Think about that for a minute. The client didn't create the trust after the lawsuit. They didn't scramble to move assets once they knew they had a problem. They made the decision years earlier, before anyone ever filed a claim against them. That's a perfect example of how asset protection is supposed to work.
Who Should Consider a DAPT?
Now, before everyone runs out and starts asking for a Domestic Asset Protection Trust, let me say this: most people don't need one.
If you're buying your first rental property or just started a side business, I'm probably talking to you about an LLC, good insurance, and a revocable living trust long before I'm talking about a DAPT. This strategy is for people who've reached a different stage. The more you've built, the more you have to protect.
A DAPT is worth considering if you've accumulated significant personal assets that aren't already protected by retirement account rules or your state's homestead exemption. It can also make sense if your profession or business naturally exposes you to more liability.
Some of the people I have this conversation with most often include:
-
Business Owners
As your business grows, so does your exposure. Even if you've done a great job separating business and personal assets with LLCs and corporations, there may still be valuable personal assets that deserve another layer of protection.
-
Real Estate Investors
If you've spent years building a real estate portfolio, chances are you've accumulated investment accounts, cash reserves, land, or second homes along the way. Those assets may be worth protecting separately from the properties themselves.
-
Professionals With Higher Liability Risk
Doctors, attorneys, developers, contractors, executives, and other professionals often have more exposure to lawsuits than the average person. When you've worked hard to build wealth, protecting it should become part of the overall plan.
-
Individuals With Significant Personal Wealth
A DAPT isn't based on your income. It's based on what you've built.
In general, I don't even start having this conversation until someone has at least seven figures in exposed assets. That doesn't mean a million-dollar net worth automatically means you need one. It depends on where your assets are, how they're titled, and what risks you actually face.
That's why the answer is almost always, "It depends."
What Assets Should Go Into a DAPT?
Not everything belongs in a Domestic Asset Protection Trust. I generally recommend looking at assets you plan to hold for the long term, especially those that aren't already protected under other laws.
Some good candidates include:
- Taxable brokerage and investment accounts
- Cash reserves
- Farmland, ranches, and other land holdings
- Vacation homes
- Second homes
- Cryptocurrency and other long-term investments
- Certain other valuable personal assets
For example, let's say you've built a $1 million brokerage account that you intend to keep invested for retirement or pass on to your family. You could transfer that account into a properly structured DAPT, continue benefiting from the investment income under the trust's terms, and create another layer of protection against future creditors.
The same concept may work for a second home, a family ranch, or a cryptocurrency portfolio you intend to hold for years. The important question is whether you're comfortable placing that asset into an irrevocable trust for long-term protection.
Now, what I generally wouldn't put directly into a DAPT is an active operating business or an entire rental property portfolio. Those assets often require more flexibility, and rental properties also create their own liability exposure. I typically prefer using properly structured LLCs for those activities and reserving the DAPT for certain long-term assets that need additional protection.
Notice what else is missing from that list: retirement accounts. In many cases, retirement accounts already receive strong protection under federal or state law. Depending on where you live, your primary residence may also receive significant homestead protection. That's why every DAPT strategy starts with one simple question: Which assets actually need another layer of protection? Once we answer that question, the planning becomes much easier.
How Is a Domestic Asset Protection Trust Taxed?
Here's another reason I like this strategy: A properly structured DAPT doesn't necessarily create a complicated new tax situation.
Many DAPTs are designed as grantor trusts for federal income tax purposes. That means the income generated by assets inside the trust continues to be reported on your personal Form 1040, just as it was before you transferred the assets.
For example, if your brokerage account earns dividends or interest after you transfer it into a grantor DAPT, that income generally continues to be reported on your individual tax return. You typically don't have a separate federal trust income tax liability simply because those assets are now held in the DAPT.
That's an important distinction because non-grantor trusts can reach the highest federal income tax brackets at much lower income levels than individuals.
Of course, the tax treatment depends on how the trust is drafted, and income tax reporting isn't the only tax consideration. Funding and administering a DAPT should be coordinated with your overall tax and estate plan.
What Are the Limitations of a DAPT?
As much as I like this strategy, a DAPT isn't a magic shield that protects everything from everyone. There are some important limitations you need to understand before setting one up.
1. It's an Irrevocable Trust
Once you transfer an asset into a DAPT, you can't simply change your mind and pull it back into your personal name whenever you want. You may still receive distributions or benefit from the asset, but those rights are governed by the trust agreement and applicable law. Which, again, is why I recommend using a DAPT for assets you're comfortable holding inside the trust for the long term.
2. Existing Creditors Can Still Challenge Transfers
A DAPT is designed for proactive planning. If you transfer assets to avoid a creditor whose claim already exists, that transfer may be challenged and reversed. There are also state-specific waiting periods, exceptions for certain creditors, and other requirements that can affect whether the protection holds up.
3. Bankruptcy Creates Additional Risks
Federal bankruptcy law has its own rules. Under certain circumstances, a bankruptcy trustee can challenge transfers made into a self-settled trust within 10 years before a bankruptcy filing if the transfer was made with actual intent to hinder, delay, or defraud a creditor. That doesn't mean every DAPT automatically fails if you file bankruptcy within 10 years. It does mean you shouldn't assume state asset protection laws will override federal bankruptcy law.
4. You Can't Make Yourself Insolvent
You also need to retain sufficient assets outside the DAPT to pay your bills and meet your financial obligations. If transferring assets into the trust leaves you unable to pay your debts, you could create serious problems for the trust's creditor protection. I want clients to protect their wealth, not put themselves in a financial bind just to fund a trust.
Do You Still Need an LLC If You Have a DAPT?
Absolutely. A DAPT doesn't replace an LLC. It doesn't replace your estate plan. It doesn't replace insurance. Think of your asset protection strategy like building layers.
Your LLC protects your business activities. Your revocable living trust helps manage your estate and avoid probate. Insurance helps transfer financial risk. A Domestic Asset Protection Trust protects certain personal assets that might otherwise remain exposed.
Keep in mind that your revocable living trust and your DAPT serve different purposes. Your living trust helps organize your estate and transfer assets to your heirs. A DAPT is a separate, specialized trust designed to protect certain assets from future creditors while allowing you to remain a beneficiary.
The strongest asset protection plans are built by combining multiple strategies that each do a different job.
Can You Use a DAPT If You Don't Live in a DAPT State?
Yes, in some cases. As of 2026, 21 states have enacted some form of Domestic Asset Protection Trust legislation. Just because your state doesn't have Domestic Asset Protection Trust laws doesn't automatically mean you can't benefit from a DAPT. Depending on your situation, it may still make sense to establish a trust under the laws of a state that does recognize them.
For example, if you live in Arizona, which doesn't have its own DAPT statute, but you own a substantial brokerage account. You may be able to establish a Utah DAPT and transfer that account into the trust, with the proper trustee and administration in Utah. A brokerage account is often easier to structure this way than real estate because it isn't permanently tied to a particular piece of land in your home state. We've had success helping clients use Utah DAPTs to protect investment assets, even when they lived elsewhere. But I want to be clear: Creating a Utah or Nevada DAPT doesn't guarantee that a court in another state will recognize all of its protections.
That said, the strategy is generally strongest when everything lines up. If you live in a DAPT state, own assets there, and any potential legal dispute is governed by that state's laws, your DAPT is likely on much stronger footing. Once multiple states become involved, things get more complicated. In fact, the U.S. Supreme Court has never settled how these laws should apply across state lines, which means every situation has to be evaluated based on its own facts.
That's why this isn't a strategy to copy from an online article or generic trust template. Where you live, where your assets are located, and where your liability exists can all influence whether a DAPT is the right tool, and how much protection it may ultimately provide.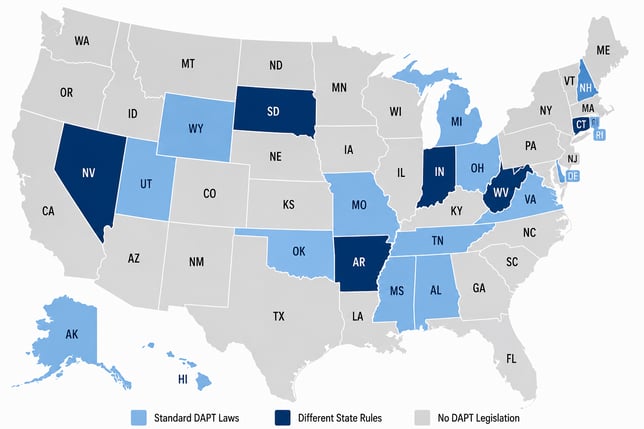
So, Is a DAPT Worth It?
A Domestic Asset Protection Trust isn't where I start. But for the right person, it’s absolutely worth it.
First, I want to make sure you have the right LLC structure, proper insurance, and a solid estate plan. Once you've built significant wealth, especially assets like investment accounts, cash, a second home, or other non-exempt property, a DAPT may be the next layer of protection worth considering.
Ultimately, it comes down to a simple cost-benefit analysis. How much do you have at risk, and is it worth creating another barrier between those assets and a future creditor? If the answer is yes, a properly structured DAPT can be one of the most valuable asset protection tools available.
The Bottom Line
A Domestic Asset Protection Trust can be an affordable and effective way to protect your hard-earned wealth from future creditors. The key is planning ahead, choosing the right assets, and making sure your DAPT works alongside your LLCs, insurance, and estate plan.
Don't wait until a lawsuit puts your assets at risk. Book a Comprehensive Estate Planning Service with my law firm, KKOS Lawyers. We'll review your assets, identify potential exposure, and help you determine whether a DAPT makes sense for your situation.
The best time to protect your assets is before someone comes after them.

Frequently Asked Questions
How much does it cost to set up a DAPT?
At my law firm, KKOS Lawyers, we can establish certain DAPTs for under $5,000, with annual maintenance costs under $500. The actual cost depends on the trust's structure, the assets involved, and your specific needs.
Does a DAPT protect assets from existing creditors?
No. A DAPT is designed to protect assets from future creditors. Transfers made to avoid existing claims can be challenged and potentially reversed.
Is a DAPT the same as a revocable living trust?
No. A revocable living trust helps manage your estate and avoid probate, while a DAPT provides an additional layer of protection against certain future creditors. The two trusts serve different purposes and can work together.
Who benefits most from a Domestic Asset Protection Trust?
Business owners, real estate investors, professionals with higher liability exposure, and individuals with significant personal assets may benefit from a DAPT. I generally recommend considering one when you have $1 million or more in assets worth protecting.
What states allow Domestic Asset Protection Trusts?
As of 2026, 21 states have some form of DAPT legislation: Alabama, Alaska, Arkansas, Connecticut, Delaware, Hawaii, Indiana, Michigan, Mississippi, Missouri, Nevada, New Hampshire, Ohio, Oklahoma, Rhode Island, South Dakota, Tennessee, Utah, Virginia, West Virginia, and Wyoming. Each state has its own requirements and levels of protection.
Can I still access my money if it's in a DAPT?
Yes, you can still receive distributions and benefit from the assets in your DAPT. However, because it's an irrevocable trust, you can't simply withdraw money whenever you want. Distributions must follow the trust's terms.